Browse
Research
IC corner
Radar
By Kristal Research Desk
Browse by channel
Microsoft cleared the bar while Alphabet, Amazon and Intel were punished for AI spending; the Fed held at 3.75–4.00% with two dissents, and oil finished October up 15%.
Meta's plan to raise hundreds of billions through Class C shares sent the Nasdaq 100 down 2.9% on Thursday, while Treasuries had their best day in over a year and Brent hit $116.93, its highest since May
The S&P 500 rose 1.15% to a record 7,811.54 even as the 10-year Treasury touched 5.35%, a $20 billion recut of OpenAI's reported revenue knocked the semiconductor index 3.4% in fifteen minutes, and Brent held above $104.
A 29,000 September payrolls print and cooler core PCE pushed October hike odds from about 70% to roughly 20%, yet the 10-year Treasury still rose 11bp to 5.28% as AI earnings from Micron, Nvidia and Accenture carried the market.
Meta's Muse launch and AMD crossing $1 trillion lifted the Nasdaq 100 3.25% even as the 10-year yield rose 17bps to 5.17%, its highest since 2007, on hot US data and hawkish Fed voices.
A unanimous, fully-priced quarter-point increase to 3.75–4.00% mattered less than Chair Warsh refusing to call money tight, a Saudi pipeline attack sending WTI above $105, and record $6.39 diesel the Fed concedes it cannot fix.
A four-day week turned an oil-supply scare into an inflation regime: Brent gained 8.7% to $104.61, the 30-year hit its highest since 2007, and futures moved to roughly 90% odds of a September hike.
WTI settled at $91.22, up 9.32%, and September rate-hike odds whipsawed from two-in-three to a coin flip on conflicting Fed remarks, while the S&P 500 closed up just 0.09% at 7,718.6.
The S&P 500 rose just 0.49% to 7,711.76 as NVIDIA, Salesforce, CrowdStrike and Okta drove software's best day in years, before Fed Chair Warsh's Jackson Hole turn roughly doubled 2026 hike odds to about 67%.
The 30-year Treasury touched 5.33%, its highest since 2007; a one-day Treasury buyback pledge failed to hold, while gold rose 5.18%, WTI 5.15% and bitcoin roughly 20% as US debt crossed USD 40tn.
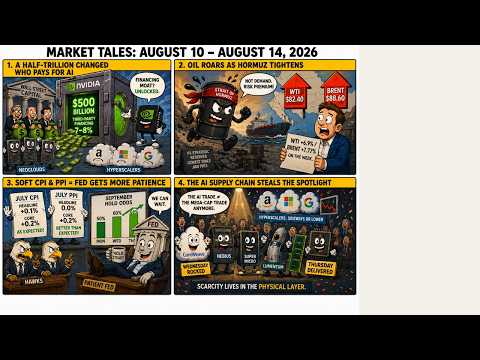
In-line July CPI and a softer PPI pushed September hold odds to roughly 68%, while a 6.9% oil week and Nvidia's six-bank financing MOUs redefined who pays for the AI buildout.
The S&P 500 rose 3.6% and the Nasdaq 100 about 5% as the AI trade roared back, yet July payrolls turned negative at -23,000 and Chair Warsh signalled willingness to raise rates in September if inflation runs hot.
The Philadelphia semiconductor index fell ~26% from its June high before Microsoft's blowout Azure quarter and a forced fund liquidation sparked an ~8% chip rally, leaving the S&P 500 up 0.96% and the Nasdaq 100 up 0.52% on the week to July 31, 2026.
Brent crossed $100 on the US–Iran conflict and a 1969-low jobless print pushed money markets to price a September hike, while Alphabet and Tesla's cash-flow-negative quarters wiped roughly $888 billion off the seven largest tech names
TSMC, ASML and Netflix all beat and raised, yet the AI basket fell ~6% on the week; IBM's pre-announcement sank shares ~25% as a cold June CPI kept the Fed patient